Short answer
In 2026, a Polish fiscal receipt showing the buyer's tax ID (NIP) for an amount not exceeding PLN 450 gross (or EUR 100 if the amount due is stated in euro) is a simplified invoice (faktura uproszczona). Above PLN 450, a receipt with NIP can still be issued, but the receipt itself is no longer an invoice. From 1 January 2027, receipts with NIP can still be issued, but they will no longer count as simplified invoices — B2B sales that require an invoice will, as a rule, be documented in KSeF, Poland's National e-Invoicing System.
"A receipt with my NIP, please" is one of the most common phrases at a Polish checkout. The customer pays, the cashier types in ten digits, the printer issues the receipt and that's it. But this convenience has an expiry date: 31 December 2026. From 1 January 2027, a receipt with NIP can still be printed, but it stops being an invoice.
Below we explain how it works today, where shops most often get it wrong and what needs to change at the till before January.
What exactly is a receipt with NIP
It is a regular fiscal receipt (paragon fiskalny) on which the cash register or fiscal printer prints the buyer's NIP. Until the end of 2026, for amounts up to PLN 450, it has the status of a simplified invoice (Art. 106e(5)(3) of the Polish VAT Act). It does not need the buyer's name or address — the NIP is enough.
For the buyer, it is convenient: one document that works as an invoice. For the shop, it is fast: no second document to issue.
Up to what amount is a receipt with NIP an invoice
PLN 450 is not a limit for issuing a receipt with NIP. It is the limit up to which a receipt with NIP can be treated as a simplified invoice. You can print a receipt with NIP for PLN 1,200 as well — it just isn't an invoice then.
| Receipt amount (gross) | What a receipt with NIP is in 2026 | What the seller does |
|---|---|---|
| up to PLN 450 (or EUR 100 when the amount due is in euro) | a simplified invoice | nothing more — the receipt is enough |
| above PLN 450 | only a fiscal receipt | for a sale to a business, issues a separate invoice — it is required (in KSeF, if the seller is covered by the KSeF obligation) |
Four rules shops most often trip over:
- The limit is gross, i.e. including VAT.
- EUR 100 applies when the amount due is stated in euro. For sales in złoty, the limit is PLN 450.
- The NIP must be entered before the sale is fiscalised. If a receipt was issued without a NIP, you cannot add it later and turn it into a business document — and you may not issue an invoice to a business for such a receipt (Art. 106b(5) of the VAT Act; penalty: 100% of the VAT, Art. 106b(6)). Obvious mistakes in a NIP already printed on the receipt (e.g. swapped digits) are treated differently — these can be corrected with an appropriate document.
- Do not issue a second invoice for a receipt with NIP up to PLN 450. In 2026 the receipt already is one. A second invoice means two documents for one sale and a risk of double VAT.
These rules cover typical domestic retail sales. The Act provides exceptions for certain special types of transactions (Art. 106e(6)), e.g. intra-EU supplies of goods.
Receipt with NIP above PLN 450
Above the limit, a receipt with NIP is only a fiscal receipt. It is not a simplified invoice and does not, by itself, give the standard right to deduct VAT. For a sale to a business, the seller must issue an invoice for that sale (the so-called invoice for the receipt, faktura do paragonu) — the obligation comes from the Act (Art. 106b(1)), not from the customer's request. Invoices "on request" apply e.g. to private individuals.
If the seller is already covered by the KSeF obligation, the invoice goes to KSeF. The obligation was introduced in stages:
- 1 February 2026 — companies with 2024 sales above PLN 200 million gross,
- 1 April 2026 — most other taxpayers,
- until 31 December 2026 — transitional relief applies: taxpayers whose sales documented with invoices subject to mandatory KSeF do not exceed PLN 10,000 gross per month may stay outside KSeF, and invoices from cash registers and receipts with NIP are excluded from KSeF.
The seller must keep the link between the invoice and the receipt it is based on — including the document number and the cash register's unique number. In the VAT records (JPK) the invoice is marked FP, so the sale is not counted twice — once from the cash register report and again from the invoice. We describe this step by step in Invoice for a receipt in KSeF.
1 January 2027: the end of the transition period
KSeF has been live since 2026, but cash registers had a transition period. It ends on 31 December 2026. From 1 January 2027:
- A receipt with NIP stops being a simplified invoice, whatever the amount. It can still be printed, but it is only a fiscal document.
- Invoices for businesses are, as a rule, issued in KSeF — even for PLN 20 (for transactions covered by mandatory KSeF).
- A cash register can no longer issue invoices. It is used for receipts.
Simplified invoices do not disappear. Only the receipt's status as a simplified invoice goes away. A simplified invoice up to PLN 450 (EUR 100) for domestic B2B sales can still be issued — from 2027 in KSeF, in the FA(3) structure, marked UPR. It is optional: a small sale can also be documented with a regular invoice. As today, the buyer's NIP is generally enough, without the full name and address.
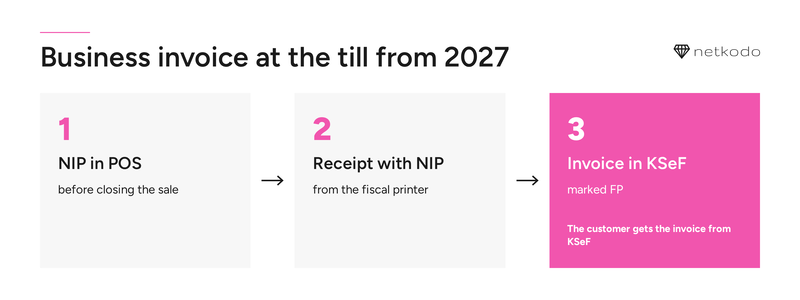
If a shop also registers business sales on the cash register, the checkout process from 2027 looks like this:
- The cashier takes the NIP before closing the sale.
- The fiscal printer prints a receipt with NIP — a fiscal document.
- The shop issues an invoice for that sale and sends it to KSeF; in the VAT records it is marked FP. This can happen automatically right after the sale, but KSeF does not change the statutory deadlines for issuing invoices. The customer gets the receipt in hand and finds the invoice in KSeF.
This is not the only permitted route. The obligation to register sales on a cash register generally applies to sales to private individuals and flat-rate farmers — a sale to a business does not have to go through the cash register just because it is B2B. In practice, though, many shops register every over-the-counter sale on the cash register, and then the process above applies.
For a shop that today handles business customers only with receipts with NIP, this is a real process change. The result? From January, every business sale means an extra document in KSeF. If the cashier has to issue it manually on a back-office computer, the December queue will grow faster than the pile of receipts in the drawer.
Penalties for KSeF errors are due to apply from 2027. In September 2026 the Ministry of Finance announced it would postpone them to 1 January 2028, but as of 30 September 2026 the change has not yet been enacted — there is only an announcement and draft assumptions. The obligation to issue invoices in KSeF from 2027 remains unchanged.
We list what to do before January in Receipt with NIP and KSeF — what changes on 1 January 2027.
Let's talk about how your shop will issue invoices from January
Book 20 minutesMost common mistakes with receipts with NIP
- "A receipt with NIP can only be issued up to PLN 450." No — it can be printed for any amount. Up to PLN 450 (until the end of 2026) it is a simplified invoice; above that, just a receipt.
- No NIP on the receipt. It cannot be added later, and you may not issue an invoice to a business for such a receipt. The fix: the cashier asks about an invoice before closing the sale.
- A second invoice for a receipt with NIP up to PLN 450 (in 2026). The receipt already is an invoice — you create a duplicate.
- Believing simplified invoices disappear in 2027. Only the receipt as a simplified invoice goes away. The simplified invoice stays — in KSeF.
- Leaving 2027 to the last minute. It is better to change the checkout process in November than in the first week of January.
How we solve it in Shopify POS: Netkodo Fiscal Gateway
In Poland, Shopify POS cannot print a fiscal receipt on its own — we covered this in Shopify POS in Poland – fiscal printer integration. That is why we built Netkodo Fiscal Gateway — a device that connects an iPad running Shopify POS to a Posnet, Novitus or Elzab fiscal printer.
If a shop registers business sales on the cash register, from 2027 the receipt with NIP will remain a fiscal document, and the actual invoice for the business will be issued in KSeF. With Fiscal Gateway, the sales assistant does it in the same place where they sell:
- The customer says they want an invoice. The sales assistant enters the NIP in Shopify POS before closing the sale.
- Fiscal Gateway prints the receipt with NIP.
- The invoice is created in the integrated invoicing software (Fakturownia, wFirma or inFakt), linked to the sale and — once the KSeF integration is configured — sent to KSeF.
No retyping data into a second system and no walking to a back-office computer.
See how Fiscal Gateway works →
2026 vs 2027 in one table
| Situation | Until 31.12.2026 | From 1.01.2027 |
|---|---|---|
| A business buys for PLN 100 | receipt with NIP = simplified invoice, outside KSeF | receipt with NIP (fiscal document) + invoice in KSeF |
| A business buys for PLN 800 | receipt with NIP + invoice for the receipt (in KSeF, if the seller is covered) | receipt with NIP (fiscal document) + invoice in KSeF |
| Simplified invoice up to PLN 450 (B2B) | a receipt with NIP can be one | in KSeF (marked UPR) |
| Invoice issued on a cash register | allowed, outside KSeF | not allowed |
| A private individual asks for an invoice | paper, PDF or in KSeF (optional) | no change |
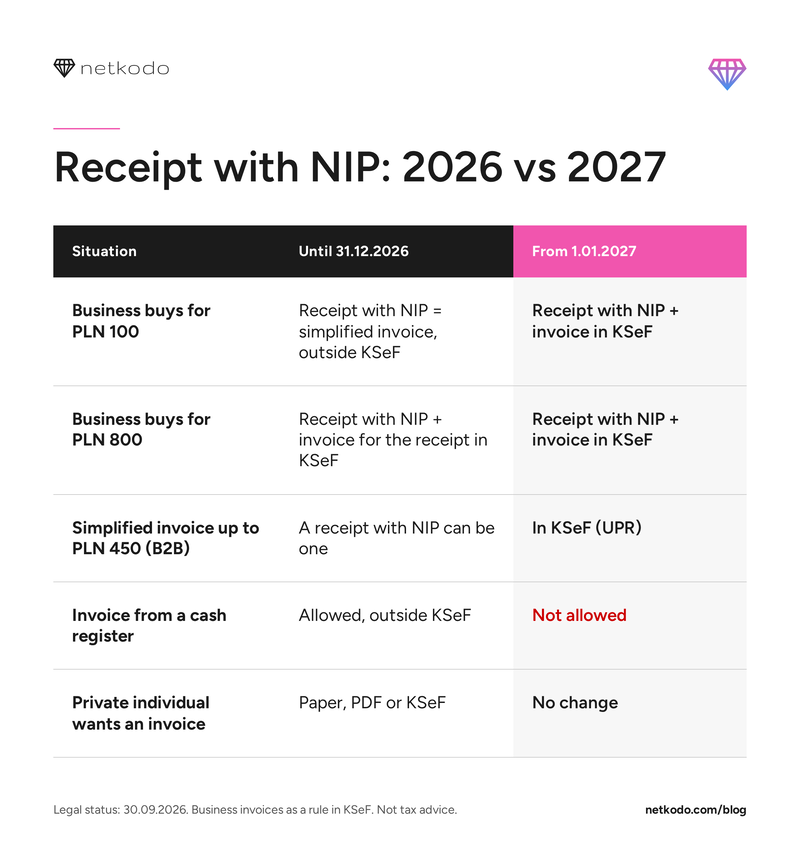
Graphic to download and share.
FAQ
Up to what amount can a receipt with NIP be issued?
A receipt with NIP can be printed for any amount. Until 31 December 2026, however, it is a simplified invoice only up to PLN 450 gross (or EUR 100 when the amount due is in euro). Above that, a separate invoice is required for a sale to a business.
Can a receipt with NIP be for exactly PLN 450?
Yes. The limit is an amount not exceeding PLN 450 gross, so a receipt with NIP for PLN 450.00 is a simplified invoice in 2026. At PLN 450.01 it is not.
Can a receipt with NIP be issued above PLN 450?
Yes. A receipt with NIP can be issued for any amount, e.g. PLN 1,200. Above PLN 450, however, it is only a fiscal receipt, not an invoice.
Can an invoice be issued for a receipt with NIP above PLN 450?
Yes — for a sale to a business the invoice is required, whether or not the customer asks for it. It is an invoice for the receipt: the seller keeps its link to the receipt (document number and the cash register's unique number), and it is marked FP in the VAT records. If the seller is covered by the KSeF obligation, they issue it in KSeF. Condition: the buyer's NIP must be on the receipt.
Can a receipt with NIP above PLN 450 be used for business accounting?
A receipt with NIP above PLN 450 is not a simplified invoice and is not, by itself, an invoice giving the standard right to deduct VAT. For a typical business purchase you need a proper invoice. Whether the expense counts as a tax-deductible cost is a separate question from VAT deduction and depends on the documentation rules that apply to the particular taxpayer.
Can a NIP be added to a receipt after the purchase?
No. If the receipt was issued without a NIP, you cannot add the number later and turn it into a business document.
Can a wrong NIP on a receipt be corrected?
If the NIP is on the receipt but with an obvious mistake (e.g. a missing or swapped digit), the Ministry of Finance allows it to be corrected with an appropriate document. You cannot, however, enter a completely different NIP or turn a private purchase into a business one. Agree the correction method with your accountant.
Does a receipt with NIP go to KSeF?
The receipt does not go to KSeF. Until 31 December 2026, a receipt with NIP up to PLN 450 is a simplified invoice outside KSeF. From 1 January 2027, an invoice for a business is, as a rule, issued in KSeF.
Will receipts with NIP still be possible in 2027?
Yes. The cash register will still print a receipt with NIP, but it will not be an invoice. Invoices — including simplified ones, marked UPR — will be issued in KSeF.
Can a private individual get an invoice for a receipt?
Yes, on request. An invoice for a private individual does not have to go to KSeF — it can be on paper or in PDF.
This article is for information only and is not tax advice. Legal status as of 30 September 2026. Basis: Polish VAT Act of 11 March 2004 (consolidated text: Journal of Laws 2026, item 1263), Art. 106b, 106e, 106h, 145n, KSeF regulations and Ministry of Finance materials (ksef.podatki.gov.pl). For your specific situation, consult an accountant or tax adviser.
Any questions?
We help Polish shops sell on Shopify and Shopify POS in line with Polish regulations — from fiscal printers to KSeF.


